


The Semiquincentennial Dollar: A Deep Dive into Long-Term ROI, Privy Rarity, and Alternative Asset Allocation for the 2026 Trump $1 Coin
September 17, 2026Selling 2026 SemiQ $1 July 4th Privy Coins: Auction Fees, Timing, and Strategies for a Stronger Return
September 17, 2026
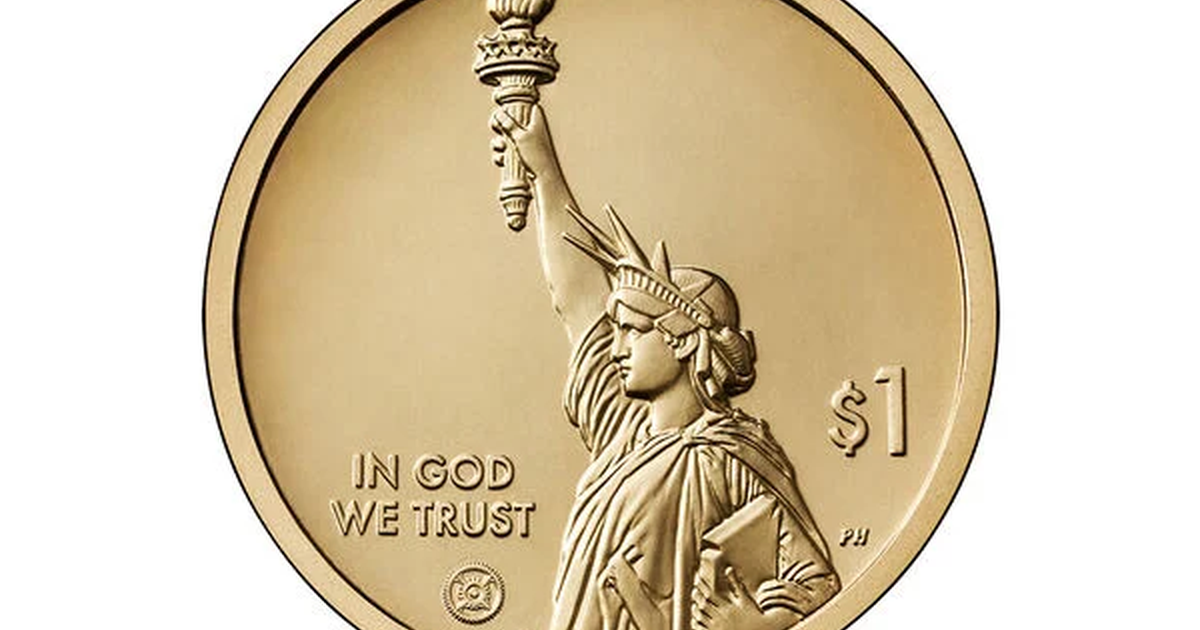
Inherited a box of 2026 “SemiQ” $1 coin rolls or bags? I would leave the seals intact before heading to a pawn shop—or accepting a quick offer. Ordinary dollar coins, collectible original packaging, and an authenticated special issue can bring very different returns. And that eye-catching online asking price? It is not necessarily a value an executor can defend.
My approach to an inherited coin collection starts with preservation, not selling: identify what is there, protect its condition, document ownership, and establish the correct valuation date. Only then do I compare selling options. I enjoy a privy hunt as much as any collector, but estate assets call for evidence, accountability, and a realistic estimate of what beneficiaries will receive.
The discussion surrounding these reported coins shows how quickly excitement can outpace documentation. Collectors debated $61 rolls, $154.50 bags, a reported July 4th privy mark, and speculative prices of several hundred dollars. They also disagreed about scarcity, distribution, and what a sealed package might hold.
Source caution: The supplied discussion is not an authenticated U.S. Mint announcement. Its September 2, 2026 sale date, “Semiquincentennial President Donald J. Trump $1 Coin” identification, reported 250,000 privy-marked coins, and July 4th striking claims all need confirmation through official records. I would not use a forum quotation alone to establish that this issue exists as described, let alone assign it an estate value.
1. Identify the Inherited Coins Before Assigning a Value
What “SemiQ” tells you—and what it cannot prove
“SemiQ” is informal shorthand for semiquincentennial: a 250th anniversary. For Americans, 2026 marks 250 years since the adoption of the Declaration of Independence in 1776. That historical connection can draw interest from coin collectors, historians, and people who collect patriotic memorabilia.
But a nickname is not an official attribution. It tells me nothing conclusive about the issuer, denomination, composition, mint mark, or legal-tender status. A privately made souvenir and an official United States coin need different descriptions—and may have very different numismatic value.
Before discussing price, I would match the inherited material to dependable documentation:
- Product identity: Copy the exact package wording, product number, and named issuer into the inventory.
- Purchase records: Keep invoices, order confirmations, packing slips, and related correspondence together.
- Physical details: Photograph visible coin faces and all packaging without breaking intact seals.
- Official specifications: Verify the design, denomination, metallic composition, mint marks, and any special mark against official records.
- Chronology: Make sure purchase and shipping dates agree with the documented release schedule.
I would never label these pieces gold, silver, or valuable scrap simply because of their color or a forum comment. Composition needs independent confirmation. A purported official issue featuring a named president also deserves a check against the applicable authorizing legislation and official product records—not an assumption based on a discussion title.
Build an estate inventory before anything moves
Give each roll, bag, or loose-coin group an inventory number. Note its location, apparent contents, packaging condition, and whether it has been opened. Be precise: “100 coins stated on sealed bag” is not the same as “100 coins counted.”
Before taking anything to a dealer, confirm that the executor, administrator, or other authorized representative has approved the transfer. A family’s understanding about who “gets the coins” does not necessarily establish legal authority to sell estate property.
2. Separate Face Value, Purchase Price, and Market Value
The forum’s purchase prices are not estate appraisals
The discussion cites two purchase options:
- 25-coin roll at $61: $2.44 per coin, with $25 in face value if every piece is a genuine $1 legal-tender coin.
- 100-coin bag at $154.50: $1.545 per coin, usually rounded to $1.55, with $100 in face value under the same assumption.
That arithmetic explains the appeal of bags: a lower purchase cost per coin. Rolls appealed to collectors who preferred the packaging format or simply did not want 100 coins.
Neither preference tells an executor what the inheritance is worth today. The original buyer paid a premium above face value, but the secondary market may preserve that premium, increase it, or erase it. Shipping and other purchase expenses do not automatically come back when the coins sell.
I keep these four figures separate when evaluating a collection for sale:
- Face value: The denomination of genuine legal-tender coins.
- Original acquisition cost: What the deceased paid, backed by purchase records.
- Fair market value: A supportable value for the required date and appraisal purpose.
- Net liquidation proceeds: What remains after commissions, grading, shipping, insurance, and other selling expenses.
Why a $400 presale does not establish value
Forum participants reported privy-related presales around $400 to $600 or more. What the discussion does not provide is a dependable series of completed, paid, delivered transactions at those prices. An asking price, a canceled order, and a listing with an undisclosed accepted offer are not equivalent evidence.
For an appraisal, I want completed sales of the same verified issue and variety, with comparable condition, certification, and packaging. Timing matters, too. Launch-week excitement can say little about the market a few months later.
Seller takeaway: Save actual transaction records, not just screenshots of hopeful listings. If speculative presales are the only evidence available, the valuation should state that limitation plainly.
3. Verify the Privy Claim Without Gambling With Estate Assets
A privy mark does not automatically mean error or rarity
A privy mark is a small distinguishing device included as part of an authorized design or issue. It is not automatically a mint error. Nor is it interchangeable with a mint mark, which identifies a production facility.
The thread quotes what participants describe as Mint language stating that 250,000 specially marked coins were struck on July 4th and randomly included in rolls and bags. If official records confirm that account, the date-specific production history would add collecting interest. It would not, by itself, establish a rare variety or a particular market price.
I also separate issue-level production history from individual provenance. Official confirmation of a striking date supports the history of an issue. Receipts, estate records, and documented transfers establish the ownership trail of a particular coin. A timestamp on a shipping box cannot prove when the coins inside were struck.
“Three per bag” is an average—not a guarantee
Some participants estimated a privy rate of roughly 3%. That figure rests on assumptions about the total eligible coin pool and whether special pieces appeared only in certain products. Those assumptions were disputed within the thread itself.
Even if each coin independently had a 3% chance of carrying the mark, the numbers would mean:
- A 25-coin roll would average 0.75 privy coins, with no guarantee of finding one.
- A 100-coin bag would average three privy coins, with no guarantee of finding three.
- The chance of finding at least one privy would be about 53% in a roll and 95% in a bag.
These are illustrations, not verified odds for the reported products. Packing could produce clusters rather than independent random distribution. More ordinary coins entering circulation would not necessarily change the odds within a separate collector-product pool. The key question is where the privy-marked coins were actually allocated.
Should an executor open inherited rolls or bags?
My default is simple: preserve intact packaging until the evidence supports a selling strategy. Opening a roll might reveal a desirable variety. It might also destroy a premium collectors pay for documented original packaging.
Before approving a search, I would compare:
- Completed sales of comparable unopened products.
- Completed sales of ordinary coins removed from their packaging.
- Verified sale prices for authenticated privy examples.
- The expense of examination, grading, and selling coins separately.
- The strength of the evidence for original packaging and privy distribution.
A sewn bag does not prove that its contents are untouched. An apparently intact roll is not proof against manipulation, either. If the estate opens a package, document the process and keep the packaging. Never describe opened material—or material with an uncertain history—as “unsearched.”
4. Get Estate Taxes and Inherited Basis Right
Estate tax and inheritance tax are not the same
In the United States, federal estate tax generally applies to the transfer of a taxable estate. There is no separate federal inheritance tax imposed simply because a beneficiary receives coins. Some states impose estate taxes, some impose inheritance taxes, and their rules and exemptions differ.
A state inheritance tax may depend on the beneficiary’s relationship to the deceased. State estate-tax thresholds can also differ sharply from the federal threshold. What matters is the estate’s overall situation—not merely that one of its assets is collectible currency.
I ask the estate’s attorney or tax adviser to establish:
- The deceased’s date of death and domicile.
- The applicable federal and state filing requirements.
- Who legally owned the collection, including any joint ownership or trust arrangement.
- Whether probate, tax, or beneficiary-allocation rules call for an appraisal.
- The required valuation date and valuation standard.
Even when no federal estate tax is due, a modern coin collection may still need careful documentation for probate, basis, and a fair division among beneficiaries.
The right value depends on the right date
Inherited property generally receives a basis tied to its fair market value at the decedent’s death, subject to exceptions. A properly elected alternate valuation may apply in qualifying federal estate-tax circumstances. It is not permission to choose whichever date happens to show the lowest coin prices.
That distinction matters in a volatile collector market. A verified privy coin’s value at death and its eventual sale price answer different questions. A later auction result may inform a retrospective appraisal, but it does not automatically replace the value required for the earlier date.
Suppose an inherited coin has a properly established $150 basis and later brings $220 after allowable selling expenses. The gain may be $70, subject to the applicable tax rules. For inherited property, the original owner’s purchase price generally is not the controlling basis figure.
For individuals, long-term collectibles gains can face a maximum federal rate of 28%. That is not a flat 28% tax on every inherited coin sale. Inherited property generally receives long-term holding-period treatment, but the taxpayer’s circumstances, state taxes, and whether the estate or beneficiary sells all matter. Loss treatment also depends on how the property was held and used.
Executor takeaway: File the appraisal, inventory, sale statement, and expense records together. A sale below the deceased’s purchase price does not, on its own, establish a deductible tax loss.
5. Request an Appraisal That Answers the Estate’s Question
A dealer’s buying offer is not an independent appraisal
A cash offer tells me what one buyer will pay today. An insurance valuation may address replacement cost. An estate appraisal may need to establish fair market value as of an earlier date. Those are different questions, and they can produce different figures without contradiction.
I look for an appraiser with relevant numismatic expertise and estate experience. Professional membership can help, but I still ask about comparable assignments, methods, fees, and conflicts of interest. A fee calculated as a percentage of the appraised value is a warning sign.
A useful written appraisal should include:
- The client, intended use, intended users, and effective valuation date.
- An itemized description matched to the estate inventory.
- Photographs and a clear explanation of what was inspected.
- Authentication, variety, and condition findings, including unresolved questions.
- Comparable sales and the reasoning behind material adjustments.
- Any assumptions about sealed packaging and unseen coins.
- The appraiser’s qualifications, fee arrangement, and relevant disclosures.
Condition matters—but grading must justify its expense
Fresh packaging does not guarantee flawless coins. Contact marks, abrasions, spots, and fingerprints can reduce numismatic value and eye appeal. I would not treat a seller’s “mint condition” description as a grade: neither a roll nor a bag establishes Proof manufacture or a high Mint State grade.
When deciding whether a coin merits professional grading, I focus on:
- Original surfaces: Check for hairlines, unnatural gloss, and evidence of polishing or other surface alteration.
- Contact marks: Judge how strongly they interrupt focal areas and open fields.
- Luster and strike: Compare both with expectations for the verified issue and manufacturing method.
- Spotting and discoloration: Distinguish toning or patina from potentially damaging changes that need specialist assessment.
- Privy authenticity: Match the device to verified official references and rule out added or altered marks.
Please do not clean the coins. A well-meant polish can permanently harm original surfaces and collectibility. Handle loose examples by their edges, place them in suitable inert holders, and avoid soft PVC-containing storage materials.
PCGS or NGC certification may be worth considering, but first confirm that the service recognizes the particular issue and claimed variety. The likely benefit should justify grading fees, shipping, insurance, and the wait. A numerical grade is not a promise of a selling price.
6. Avoid Inheritance Scams and Choose the Right Selling Venue
Pressure tactics that should stop a sale
Inherited collections can attract pressure, especially when relatives want a quick distribution. I would pause and investigate any proposal involving:
- Guaranteed discoveries: A promoter or buyer insists that every unopened package contains a valuable privy coin.
- Unverifiable certificates: A document claims authenticity without naming a credible issuer or explaining the examination.
- Advance “release” payments: Someone demands a tax or processing payment to an unrelated party before purchasing the coins.
- Instant-sale pressure: An offer supposedly expires before the estate can obtain independent advice.
- Unlogged custody: Coins leave the estate without an itemized receipt and written terms.
- Suspicious payment arrangements: Overpayments, refund demands, or requests to abandon a selling platform’s protections.
For a certified coin, check the certification with the grading service and compare available photographs and holder details. A genuine certification number can be copied. The number alone does not authenticate the coin or holder in front of you.
Choose an auction house that fits the collection
The best venue depends on the material, its likely value, and the buyers it needs to reach. A national numismatic auction house may suit an important certified variety or substantial collection. A reputable regional specialist may sell a modest inheritance more economically. Common opened coins may be best handled by a coin dealer.
I would consider firms such as Heritage Auctions or Stack’s Bowers only after checking current consignment requirements and the fit with an upcoming sale. A familiar name does not guarantee acceptance—or better net proceeds for a small lot of modern coins.
Before consigning, ask each prospective auctioneer:
- Have you sold this exact verified issue or genuinely comparable material?
- Which completed sales support your estimate?
- What seller commissions and additional charges will apply?
- Would these rolls and bags do better together or in separate lots?
- Would certification or a reserve help, and at what cost?
- Who insures the coins, and exactly when does coverage begin?
- What charges or conditions apply if a lot is unsold or withdrawn?
- When should the estate expect payment?
I compare dealer offers with estimated net auction proceeds, not headline results. Published auction prices may include a buyer’s premium that never reaches the consignor. A $500 hammer price less a 15% seller commission leaves $425 before other charges. The written contract—not the optimistic estimate—determines what the estate keeps.
7. Preserve the History, Verify the Privy, and Sell on Evidence
The reported 2026 “SemiQ” dollar rolls and bags have an appealing collector story: an American anniversary, a possible date-specific privy mark, original packaging, and the chance of discovery. If official records authenticate the issue as described, that semiquincentennial connection could attract buyers well beyond dollar-coin specialists.
Still, historical interest, scarcity, and market value are separate questions. A reported population of 250,000 guarantees neither a high price nor a low one. Demand, distribution, condition, authentication, and the supply actually offered for sale all shape collectibility and price.
For an inherited collection, my checklist stays practical:
- Verify the issue against official records, not repeated forum claims.
- Inventory the inheritance and establish who has authority to sell.
- Preserve packaging and surfaces while comparing selling options.
- Obtain an appropriate appraisal for the required date and purpose.
- Coordinate tax treatment with the estate’s attorney or tax adviser.
- Choose the venue by net return, security, and access to relevant collectors.
- Retain a complete paper trail for beneficiaries and tax reporting.
A pawn shop is not automatically the wrong choice, and an auction is not automatically the right one. The costly mistake is choosing before you know what the estate owns. I would rather preserve a collection’s history and document a fair sale than chase an unverified privy promise. That is how an executor protects both the inheritance and the people entitled to share it.
Related Resources
You might also find these related articles helpful:
- The Semiquincentennial Dollar: A Deep Dive into Long-Term ROI, Privy Rarity, and Alternative Asset Allocation for the 2026 Trump $1 Coin – For collectors and historians looking to put money into hard assets, numismatics offers something special. I want to tal…
- The Silver & Gold Content of SemiQ 2026 $1 Coin Rolls & Bags on Sale Sep 2nd: Let the Privy Hunt Begin Explained – Sometimes the metal inside a coin is worth more than the face value stamped on it. That’s the dream every stacker …
- The Ultimate Roll Hunter’s Guide to the 2026 SemiQ Trump $1 Coin: Cherry Picking the July 4th Privy – The Hunt Is On: Why You Don’t Need a Dealer to Find the Gold Welcome to the ultimate roll hunter’s guide to the 2026 Sem…
